Many responsible parents start their college plan with a 529. You set up a monthly contribution, feel good about getting started, and assume you’re on the right path. You weighed your options, made a choice and took action. That instinct is right.
Pros: A 529 plan is a valuable tool. It allows families to set aside money for qualified education expenses and grow it tax-free. Cons: A 529 plan introduces a significant market risk, and has limited investment options, restrictions on how you spend your money, and nothing that protects your family in case of a tragedy.
That’s where Kiddos comes in. We provide more options and a smarter choice.
A 529 is designed to be liquidated during college.
That creates a risk:
How much is the risk? There is a >50% chance that the market will fall 15% or more the two years before college or during the 4 years of college.
Kiddos reduces the risk that a market downturn during college will prevent you from paying for college by keeping your investment growing during college and after.
529s, rightly, claim being tax exempt a major benefit over a traditional investment account. But Taxable vs. Tax Exempt aren’t the only 2 options.
There are well defined hacks to reduce and defer your taxes. Your choice should be driven by how much you have left after you pay your taxes.
529 plans offer Index Funds, Bond Funds, and Target Date Funds (TDF) which combine Index and Bond funds By far, most parents select TDF. The strategy is to save what you can before college and borrow the difference when you get there. At most you’re saving for 18 years.
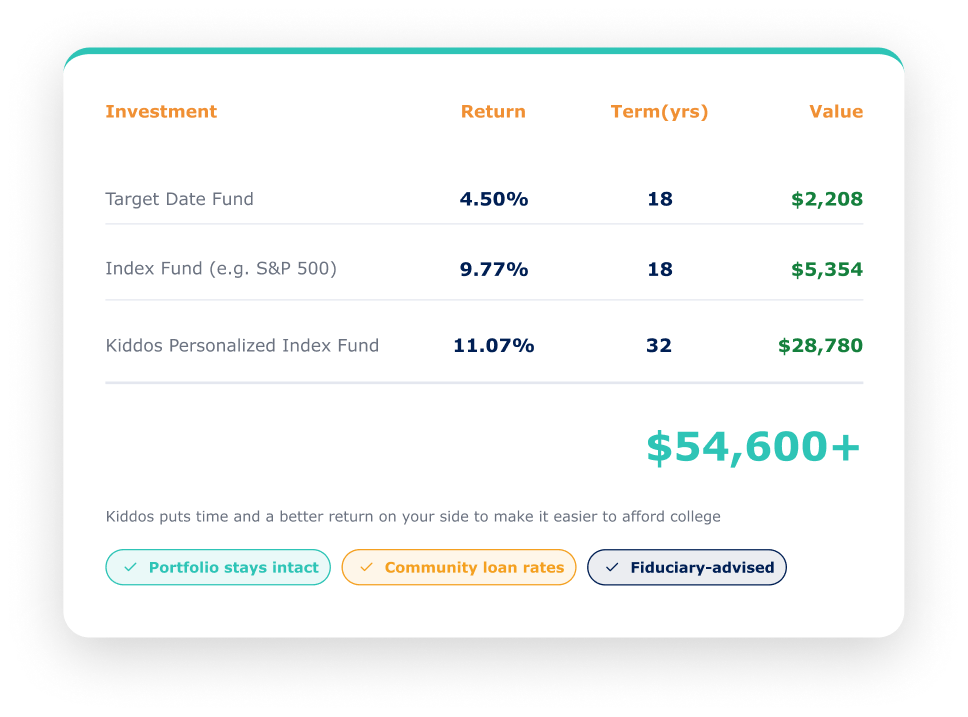
Kiddos takes a different approach – don’t sell your investments to pay for college. Borrow the funds to pay for college and let your investments grow during college and then use your investments to gradually pay off your loan. That means your investments have been growing for 32 years to pay off a 10 year loan. The math is on your side.
In addition, Kiddos makes a personalized index fund available to Kiddos members. This uses the tax code to supercharge a traditional index fund. Backtesting show this strategy increases investments by ~1.3% / year. These strategies are typically only available to the wealthy. But not with Kiddos.
What is the benefit of time and smarter investments?
Suppose you put $1,000 in a TDF, Index, and Personalized Index Fund for 18, or 32 years.
kiddos allows you to use the funds for anything. It’s your money, you should be free to use it anyway you want, something you can’t do with a 529.
Every Kiddos membership automatically includes life insurance, so no matter what life throws your way, your child’s education is protected. You safeguard your home and your car — your kid’s future deserves the same safety net, and with Kiddos it’s built right in. (And no, we don’t earn a commission on it.)
“Like many parents, we opened 529 plans for our twins and started saving every month. It felt like the responsible thing to do. But I eventually realized we had quietly chosen a ‘save and spend’ strategy for college while investing and growing everywhere else in our financial life.”
— Jon DeVries, Founder & CEO, Kiddos Capital
Over time, that realization led to a different approach. Instead of saving for 18 years and hoping the balance is enough when tuition arrives, Kiddos focuses on a longer term Invest & Grow strategy, allowing investments to stay invested while borrowing is planned strategically in advance.
The goal isn’t simply to pay for college. It’s to build long-term family wealth along the way.
Kiddos Capital isn’t another type of savings account. It’s a membership designed to bring multiple financial tools together in one coordinated plan. Members gain access to:
A direct index investment strategy with tax-loss harvesting designed to keep more of your money growing over time.
Group-priced term life insurance helps ensure the college plan stays intact if something happens to a parent.
Through membership scale, Kiddos seeks better loan rates and benefits than most families can negotiate on their own.
A fee-only advisor coordinates your investment strategy, insurance protection, and borrowing plan as your family’s needs evolve – creating a system designed to grow wealth over time, not simply spend down a college savings account.
College costs are rising quickly, and every family’s situation is different. Start by estimating the future cost of college for your child and see how a Kiddos Plan could work alongside (or beyond) a 529.
Use the Kiddos Cost of College Calculator and request a sample plan for your family to get started.