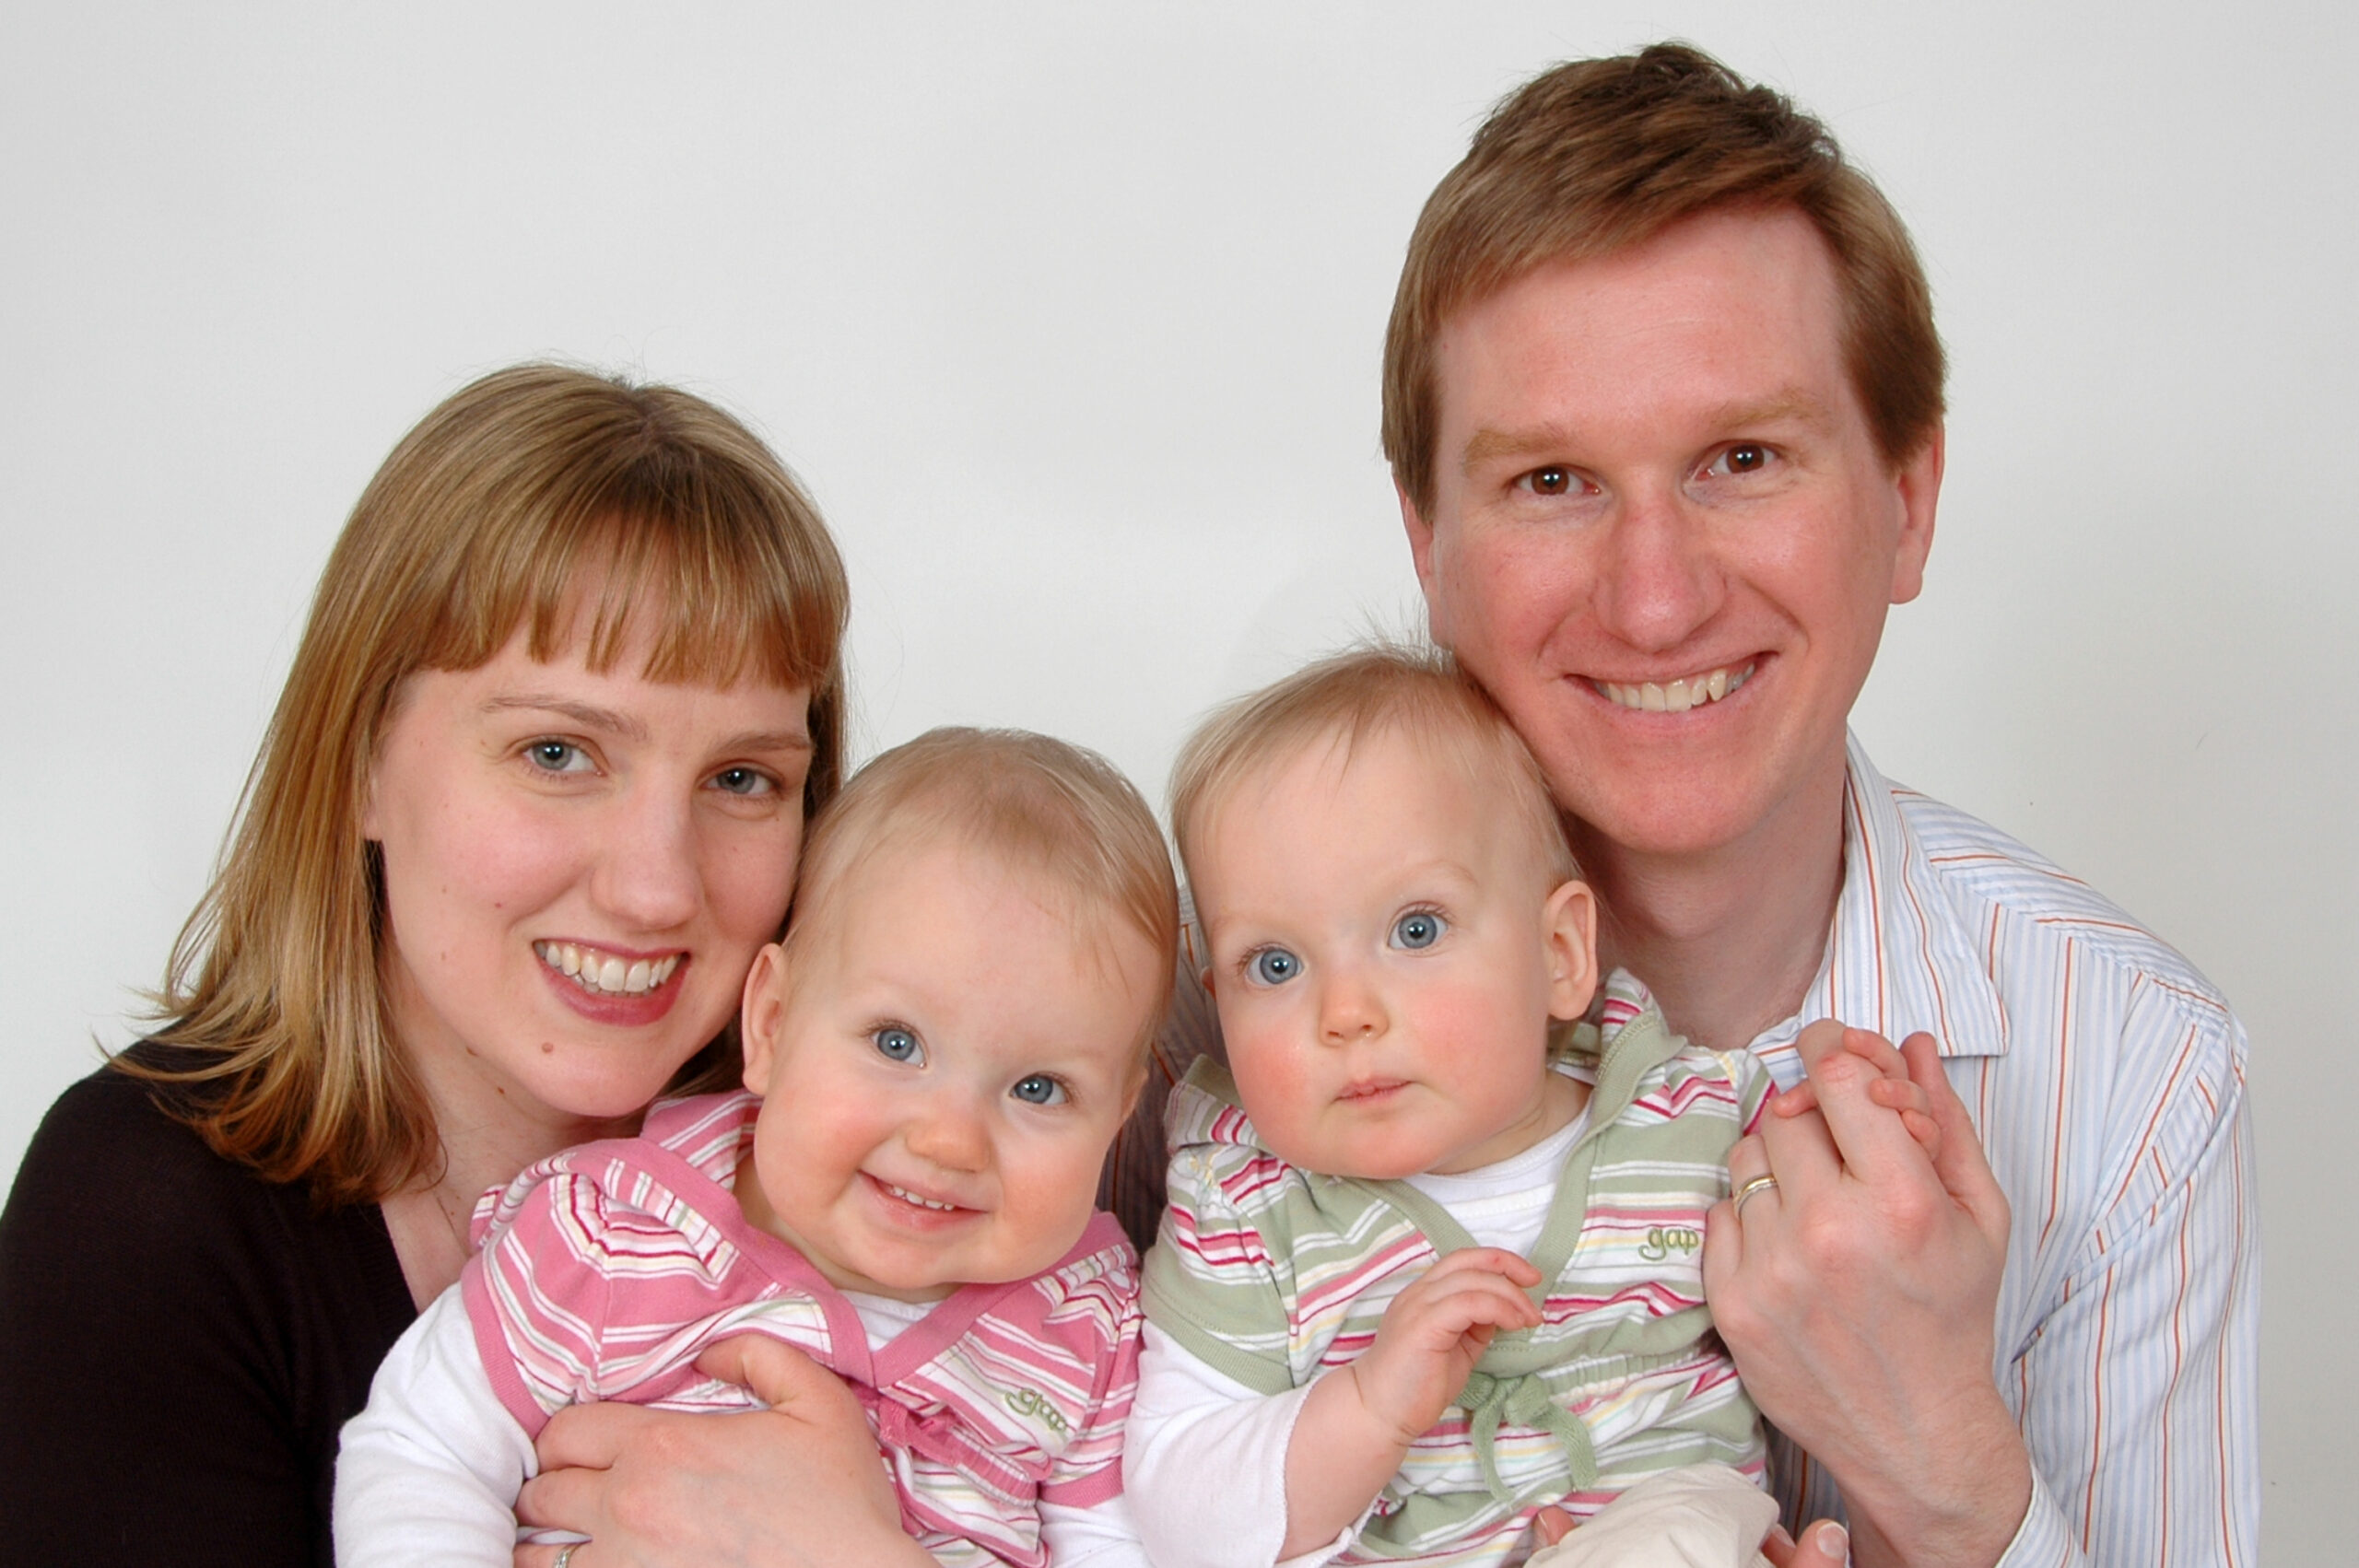
Our twins graduated from high school in 2025. During the prior 18 years, with visions of what would come next, we received all the traditional advice from multiple people and did all the things young parents are “supposed” to set our kids up for success and prepare for retirement. We thought that the plan would be going to college, but only one of the twins went to college. We learned a lot about parental and financial flexibility and what works, or doesn’t, and why. Spoiler alert … not everything worked out.
I founded Kiddos to make it work out for more families by creating a system to help parents set their kids up for success whether that means college, trade school, starting a business, or a down payment on a home.
Equity Investments
Like many families we have 401(K)s through work and a brokerage account. After maxing out my 401(K) and getting my employer match, we invested in a brokerage account as well.
We tried following a few popular investment strategies, but the reality is that, according to S&P Global[1], over the past 15 years over 88% of fund managers underperform the S&P 500. Let that sink in.
So we converted to the strategy advocated by Warren Buffet. I used dollar cost averaging to regularly invest in SPY, an ETF that tracks the performance of the S&P 500. This approach gave us:
- Passive Investing: Simple and cost-effective method for anyone to “own the market”.
- Diversification: Index funds provide instant, broad diversification, which lowers risk compared to picking individual stocks.
- Long-Term Growth: Investing in a broad index fund captures the overall growth of the economy over the long term.
- Avoids Market Timing: This strategy acknowledges the difficulty of timing the market and instead relies on the economy’s historical upward trends.
The Role of Dollar-Cost Averaging
- Systematic Investment: It’s a steady, automatic investment plan to buy index funds at regular intervals, which is dollar-cost averaging.
- Disciplined Approach: This method encourages investors to invest a set amount of money over time, ensuring they consistently put cash to work in the market.
- Lower Average Cost: During market downturns, this strategy allows you to buy more shares, which can result in a lower average purchase price over time.
It’s kind of boring, but it’s allowed me to sleep well at night for over 20 years, and it’s done very well for me. As of September 15, 2025, the returns for SPY have been[2]:
| Annual Return | Time Frame |
| 15.9% | Last 5 Years |
| 13.7% | Last 10 Years |
| 10.7% | Last 20 Years |
| 10.7% | Last 33 Years |
And there are strategies, like Direct Indexes with Tax Loss Harvesting, that combine the simplicity and effectiveness of index investing with tax strategies that allow you to keep more of your money working for you.
Loans / Mortgage
Along the way, we bought a house and got a mortgage. We didn’t get a mortgage because we didn’t have the cash. We could have liquidated our 401(K) and brokerage account. But it’s smarter to borrow a 3% – 6% (we had a variable mortgage) while our investments were earning 10% – 11% and getting ready for our retirement.
There are lots of types of “Bad Debt” like high interest credit cards.
But there is “Good Debt” like mortgages that are planned for, have low interest rates, and builds a real asset and wealth. Real estate, which uses debt, has created tremendous wealth for many families.
College is also expensive like a house. Smart use of debt for college can create wealth just like in real estate.
Life Insurance
In August 2006, I purchased a $500,000 Term Life Insurance Policy with a $685 annual premium. I also purchased a $250,000 Universal Life (“UL”) Insurance Policy with a $2,168 annual premium. By July 2025, I had paid a total of $43,360 in premiums for the UL policy. Some of that was used to pay for the insurance and a portion was invested to build up a cash value of $43,957 that I could borrow. The annual return generated by the cash value was between 3% – 4% per year and was 3.28% for the most recent year.
The Term Insurance guaranteed that my kids could afford college if a tragedy happened. But the return on the UL policy was disappointing.
529 Plans
After the twins were born, we established 529 Plans for each of our kiddos. Over the years, we’ve consistently contributed to both of the 529 plans. The twins grandmother has also contributed every month to each 529. At the time, we were advised the safe thing to do was to put the funds in a Enrollment Dated Fund (EDF) timed fund so that the risk would decrease every year until they graduated from high school and went to college. We lived in Massachusetts when the twins were born, and we selected the NH Portfolio 2024 (Fidelity Index) which was created in 2006. The returns as of 9/12/2025 were:
| Annual Return | Time Frame |
| 5.75% | 1 Year |
| 5.87% | 3 Years |
| 3.06% | 5 Years |
| 5.09% | 10 Years |
| 4.82% | Inception |
By design our 529 fund generated a low return, but had low risk. The net results was that, even though we put 5x the national average into our 529, we were still short when we got the budget for the 4 years of college.
About 70%[3] of 529 plans are in EDF or more conservative / lower return plans. This is why the average 529 Plan has ~$30K[4] which might cover a few semesters depending on where you go to school.
College Advisors
We engaged a very sharp college advisor during their senior year, and the coach was very helpful in terms of maximizing the grants and scholarships. But they also pointed out things that we should have done 5, 10, 18 years ago to get ourselves ready.
We hired an advisor a decade or more too late, and we were a way more than dollar short.
Student Loans
I learned three major things about student loans:
First, there are a lot of options available – government and private loans for students and parents. And the cost of those loans varys a lot!!!
- Government debt is relatively easy to get, but very expensive.
- Commercial debt requires a more detailed application process, but is very inexpensive.
INSERT TABLE with Governement / Student, Govnerment/parent, Commercial
Second, while the press is full of news about how much debt students are taking on, for a bachelors degree the parents take on 2x as much debt as the student according to ….. Parents need to keep in mind that this debt is coming during a time when they are:
- Still paying expenses related to their kids, and probably helping out after college
- In their peak years to save for retirement because we, as parents, don’t want to be burdens on our kids in the future.
- May be helping out with elderly parents.
Taking on a big loan can jeopardize our ability as parents to achieve those goals.
Third, and this is subtle, the school treated government debt differently than commercial debt. The college was confident enough in getting a specific amount from the government that they deducted that amount from the bills I got. But they didn’t do that for commercial loans. The big bucket the “student and parents” were responsible for were the commercial loans.
- Taking the federal money was assured, expensive, and easy
- Taking commercial loans was uncertain, comparatively cheap, and complex
To get the best loan you need planning and more time to secure the loans that it felt like we had.
So What Did We Learn?
- Hybrid investment and insurance products are – by design – low risk, expensive, and low return products. If you want to achieve your goals, you will need to put a lot more money into those products
- Time is your friend. Start saving early and let the magic of compounding gains build wealth for you.
- Good debt, like a mortgage, can help build wealth, while bad debt can be a back breaker for your kid who is starting their first job.
- Families need a plan. Investments, insurance, and loans need to work in concert to have a successful outcome.
- College advisors, in the high schools or paid consultants, can be great when it comes to getting into a good school or maximizing grants and scholarships, but come in too late to have an impact on what you saved.
We didn’t find an evil mastermind out to soak families when it came to college. Rather it’s death by a thousand cuts over 18 years before college, 4 years in school, and then 10-20 years afterwards when you are paying back the loans.
My name is Jon DeVries and I founded Kiddos Capital to provide families a coordinated, easy to follow, and effective solution that helps families set their kids up for success wither that means college or something else.
END / Old text below.
401(K)s and Brokerage Accounts
After earning my MBA, I went through a “phase” where I used the active and highly technical investing system popularized by William J. O’Neil in “The Successful Investor”. After that didn’t work for me, I converted to a passive investment strategy advocated by Warren Buffet. I used dollar cost averaging to regularly invest in SPY, an ETF that tracks the performance of the S&P 500. This approach involves:
- Passive Investing: Simple and cost-effective method for anyone to “own the market”.
- Diversification: Index funds provide instant, broad diversification, which lowers risk compared to picking individual stocks.
- Long-Term Growth: Investing in a broad index fund captures the overall growth of the economy over the long term.
- Avoids Market Timing: This strategy acknowledges the difficulty of timing the market and instead relies on the economy’s historical upward trend.
The Role of Dollar-Cost Averaging
- Systematic Investment: It’s a steady, automatic investment plan to buy index funds at regular intervals, which is dollar-cost averaging.
- Disciplined Approach: This method encourages investors to invest a set amount of money over time, ensuring they consistently put cash to work in the market.
- Lower Average Cost: During market downturns, this strategy allows you to buy more shares, which can result in a lower average purchase price over time.
I’ve been following this method for over 20 years, and it’s done very well for me. As of September 15, 2025, the returns for SPY have been[5]:
| Annual Return | Time Frame |
| 15.9% | Last 5 Years |
| 13.7% | Last 10 Years |
| 10.7% | Last 20 Years |
| 10.7% | Last 33 Years |
Employer Match: It is also critical for your financial success to always invest enough to get the entire match from your employer. I typically save more than is needed, but the employer’s matching investment is like “free money” that helps accelerate creating wealth.
There are a lot of other active ways of building wealth (real estate, starting a business, more active stock investing, etc.), but this is a strategy that worked well for us.
Life Insurance
In August 2006, I purchased a $500,000 Term Life Insurance Policy with a $685 annual premium. I also purchased a $250,000 Universal Life (“UL”) Insurance Policy with a $2,168 annual premium. By July 2025, I had paid a total of $43,360 in premiums for the UL policy. Some of that was used to pay for the insurance and a portion was invested to build up a cash value of $43,957 that I could borrow. The annual return generated by the cash value was between 3% – 4% per year and was 3.28% for the most recent year.
Insurance has a very important role in anyone’s financial plan. And I recommend everyone have insurance. But it’s important not to treat insurance as an investment tool to generate a significant return. Over the last 5 years, the market generated a return that was ~4x more than the return of an insurance policy.
Insurance should be purchased with specific uses in mind. For example:
- Is the insurance intended to provide your child with a fixed amount of money in 18 years when they go to college in the event you pass. Term Insurance is perfect.
- Support your family long term if you pass. The insurance could be used to payoff your mortgage, replace your income, provide for your spouses retirement, or other uses. That’s a more complex discussion that Kiddos can help you with and then get you the right policy.
We included Term Insurance in the Kiddos Plan because you are insuring a specific amount for a specific amount of time. Term Insurance does this at a very affordable price.
In the future, Kiddos Capital plans to be able to offer a variety of insurance products, e.g. life, disability, and long term care, at group rates. Business offer these insurance policies to their employees. Kiddos plans to offer them to the Members. Group policies are typically available at prices that are 20%-30% less than you or I would be able to get as an individual. This will be an added benefit of your Kiddos membership that we will pass on to you.
529 Plans
After the twins were born, we established a 529 Plans for each of our kiddos. Over the years, we’ve consistently contributed to both of the 529 plans. The twins grandmother has also contributed every month to each 529 (hint, hint … you should take to your parents and family members about contributing to your Kiddos Plan). At the time, we were advised to put the funds in a timed fund so that the risk would decrease every year until they graduated from high school and went to college. We lived in Massachusetts when the twins were born, and we selected the NH Portfolio 2024 (Fidelity Index) which was created in 2006. The returns as of 9/12/2025 were:
| Annual Return | Time Frame |
| 5.75% | 1 Year |
| 5.87% | 3 Years |
| 3.06% | 5 Years |
| 5.09% | 10 Years |
| 4.82% | Inception |
While the risk in this fund is less than an index fund like SPY because the 529 invested in a lot of bonds or fixed income investments, the returns are also much lower.
College Advisors
During their senior year, we met with a college advisor with the goal of maximizing their financial aid package. The advisor was very helpful. But they also pointed out things that we should have done 5, 10, 18 years ago to get ourselves ready.
Out takeaway is that having advice all along the way would have lead to a better outcome. At Kiddos, we want to give you access to that advice from the beginning so that all of the pieces – Investments, Insurance, Loans – are all coordinated.
Student Loans
There are a lot of options available, both government and private loans for students and parents. We keep our assets under the parent’s name because it improves the financial aid package our child could get because assets in the student’s name reduce financial aid packages by more than if the asset was in the parent’s name.
But one thing we discovered was that as an individual, we didn’t have a lot of bargaining power when negotiating the terms of the loans. All we could do was shop around to get better terms.
With Kiddos, we want to be in a position where we can ask, or demand, a group discount on the loans. As Kiddos, we will be in a position where we can go to a lender and say:
“We represent 1,000 (more?) kids going to college next year. Our awesome clients have been investing for up to 18 years so have a great track record and have life insurance protecting the amount they would borrow. How much can you reduce the interest rate? Of course, we expect you will waive, or heavily discount, the origination fee for our members.”
The discounts Kiddos will negotiate on your behalf in the future will vary but are expected to be significant.
Parents Helping Parents
We are parents who created the Kiddos Plan to be the solution we wish had been available to us when our twins were born.
The 4-in-1 Kiddos Plan

We believe you need a plan where each element works together at the same time, not a bag of isolated tools. A Kiddos Plan combines:
- Investments that grow
- Insurance that protects
- Loans that bridge the gap
- Planning that ties it all together

[1] https://www.spglobal.com/spdji/en/research-insights/spiva/
[2] Curvo.eu, https://curvo.eu/backtest/en/market-index/sp-500?currency=usd, September 15, 2025
[3] Vanguard research
[4] EDI stat
[5] Curvo.eu, https://curvo.eu/backtest/en/market-index/sp-500?currency=usd, September 15, 2025